The US CPI did not dissuade the market from a Fed policy change. In fact, it increased expectations — at least initially — with the market pricing in a near 90% chance for a September rate cut.
The month-to-month CPI came in at 0.4%, with the year-on-year reading at 3.4%. Core rose by 0.3%, above the 0.2% expectation, though the year-on-year figure was unchanged at 2.4% from the prior month. Supercore month-to-month CPI came in at 0.51%, well above the 0.1% recorded last month. The year-on-year supercore rate rose to 3.01% from 2.83%.
What Is Supercore CPI?
“Supercore CPI” is an informal measure of underlying inflation that focuses on services prices excluding housing costs.
It generally removes:
- Food
- Energy
- Goods
- Housing or shelter
That leaves services such as healthcare, transportation, insurance, recreation, education, and personal care.
Many of these services are labor-intensive, so their prices can reflect wage pressures. If supercore inflation remains elevated, it suggests inflation is becoming embedded in the service economy and may be difficult for the Federal Reserve to bring down.
It is worth noting that supercore is not an official, universally standardized CPI category — analysts may calculate it differently. The Fed often pays closer attention to the similar core PCE services excluding housing measure.
In simple terms, supercore inflation tries to identify the part of inflation that may be the most persistent — the portion that does not disappear quickly when energy prices fall or supply chains improve.
Currency Market Reactions
The US dollar moved higher after the report before retracing its gains.
GBP/USD: The pair moved down to test the 50% midpoint of the last trend move higher from the end of July low (July 28), a level coming in at 1.34732. That level was also near lows from the prior week and going back to August 13. Price bounced off that level and returned above 1.3500 on the successful test. Resistance remains at the 200-hour moving average at 1.35246 and the 100-hour moving average at 1.35360.
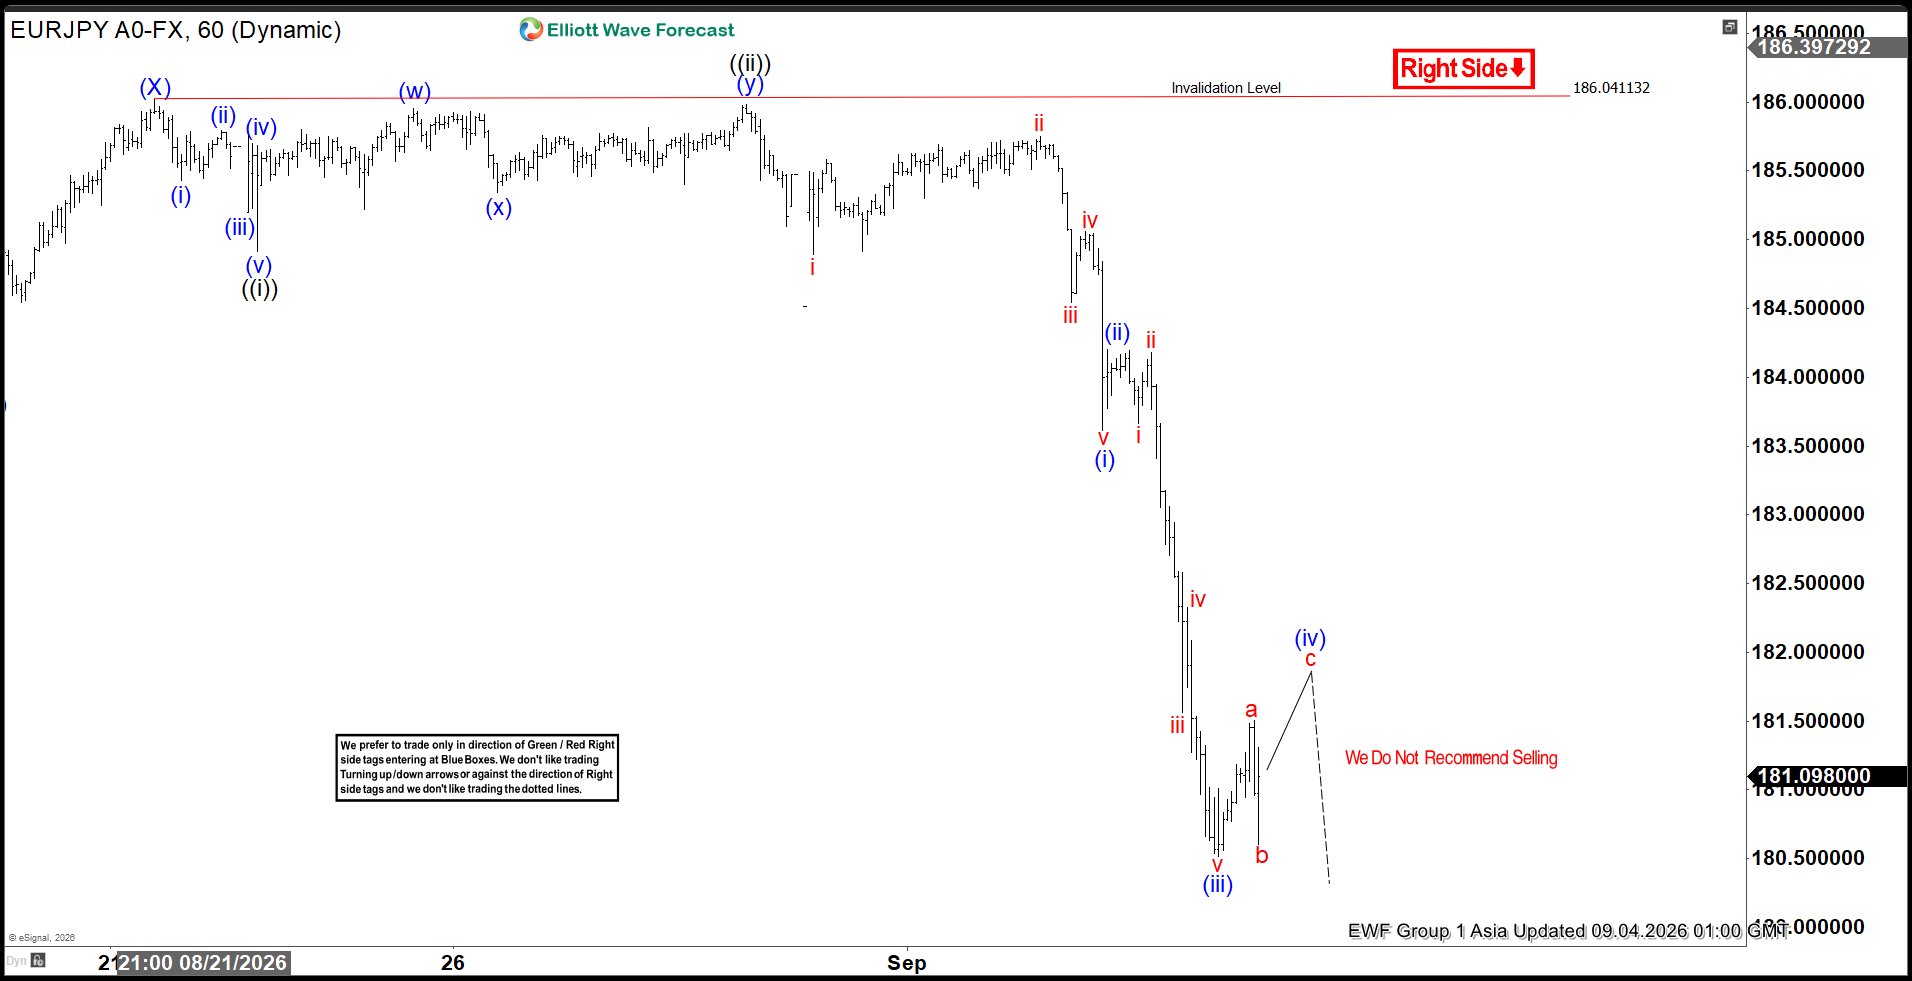
USD/JPY: The pair moved higher on the news but has since reversed to new lows for the day. Price is now back below the 100-hour moving average, which had acted as resistance on the move lower prior to the report. Trading below that level represents a bearish tilt.
EUR/USD: The pair moved below the swing area target at 1.15849 and briefly below the 38.2% retracement of the move up from the July 28 low at 1.15738. Price has since recovered above pre-release levels and trades around 1.1600. A cluster of resistance remains above, including the 200-hour moving average at 1.1613, the 100-hour moving average at 1.1623, and the 200-day moving average at 1.16316.
Equities and Treasuries
US equity futures are showing strong gains:
- S&P 500: up 70 points
- Dow Jones Industrial Average: up 517 points
- Nasdaq: up 340 points
US Treasury yields are mixed, with the curve flattening as short-term yields rise and longer-term yields decline:
- 2-year: 4.5767%, up 2.7 basis points
- 5-year: 4.7262%, down 0.7 basis points
- 10-year: 4.924%, down 2.0 basis points
- 30-year: 5.3328%, down 2.8 basis points
Selling pressure is concentrated at the short end, while buyers are moving into longer-dated Treasuries. The 10-year yield remains elevated near 5%, and the 30-year yield remains above 5.30%.
The across-the-board reversal of initial CPI reactions appears to have caught traders off guard. Markets remain volatile — knowing your key levels and following price action remain essential in this environment.