Headlines:
- US jobs report faces a higher bar as bond market tensions raise the stakes
- What is the distribution of forecasts for the US NFP?
- Stocks rebound as bond yields cool, but NFP threatens to reset the mood
- How have interest rate expectations changed after this week’s events?
- Eurozone inflation jumps to 3.8% in September as energy prices surge
- ECB policymaker Rehn flags energy and AI risks as rate outlook stays uncertain
- Gold price consolidates below $4,200 as markets turn to NFP next
- Gold finds support as dovish Fed comments signal low appetite for tightening
- Silver’s selloff pauses as key Fed members push back against October rate hike bets
- Bitcoin breaks out of the range as Fed’s Jefferson comments reduce rate hike expectations further
Markets:
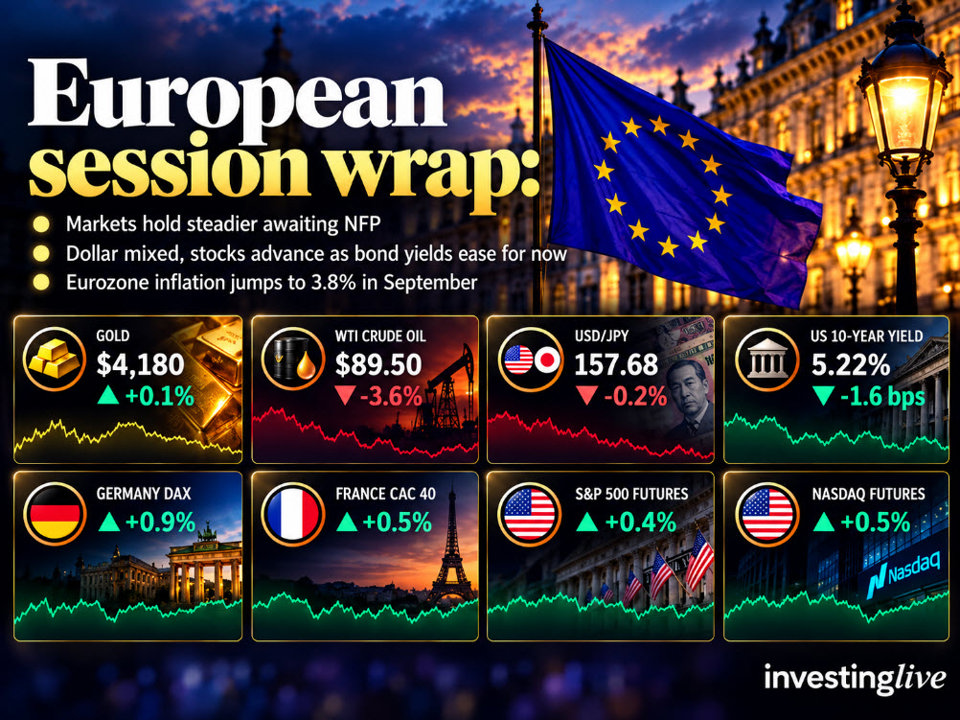
- 10-year Treasury yields -1.6 bps to 5.22%
- CHF leads, EUR lags on the day
- Gold +0.1% to $4,180
- WTI crude -3.6% to $89.50
- European stocks higher; S&P 500 futures +0.4%
- Bitcoin +2.2% to $86,511
European Session Wrap
It’s all about the US jobs report today. As markets gear towards the main event, broader conditions are looking calmer in European morning trade.
The bond market continues to be the main driver, and today yields are falling back as investors await fresh clues from the non-farm payrolls before deciding on the next move.
10-year Treasury yields are down to 5.22%, well off yesterday’s high of 5.34% — which was the highest level since 2002. In Europe, 10-year German bund yields have also cooled to 3.40%, holding well below the high earlier this week of 3.65%.
That is affording equities some breathing room. European stocks have bounced back, with US futures also building on yesterday’s rebound. The DAX is up 0.9% and the CAC 40 up 0.5%, while S&P 500 futures are up 0.4% ahead of the open.
Lower borrowing costs are helping lift stocks, alongside softer inflation worries as oil prices drop on the day. WTI crude is down over 3% to $89.50 as traders continue to weigh the situation in the Middle East, in what has been a back-and-forth week for oil prices.
Eurozone Inflation and ECB Outlook
Euro area September inflation came in hot, with the headline figure rising to 3.8%. The core estimate also nudged higher to 2.5% in September from 2.4% in August. However, the mild acceleration is still something the ECB may be able to look past ahead of their October decision. Market pricing shows roughly 28% odds of a 25 bps rate hike this month, largely unchanged from before the release.
FX and Commodities
The dollar is keeping a mixed tone on the day. EUR/USD has been pushed lower to 1.1225, while USD/JPY is also slightly down at 157.68. Gold is holding a mild bounce at $4,180, continuing to consolidate just below the $4,200 mark.
With markets in a tentative holding pattern, the US non-farm payrolls report now holds the key to whether the broader relief rally continues — or whether renewed pressure in the bond market reasserts itself before the weekend.